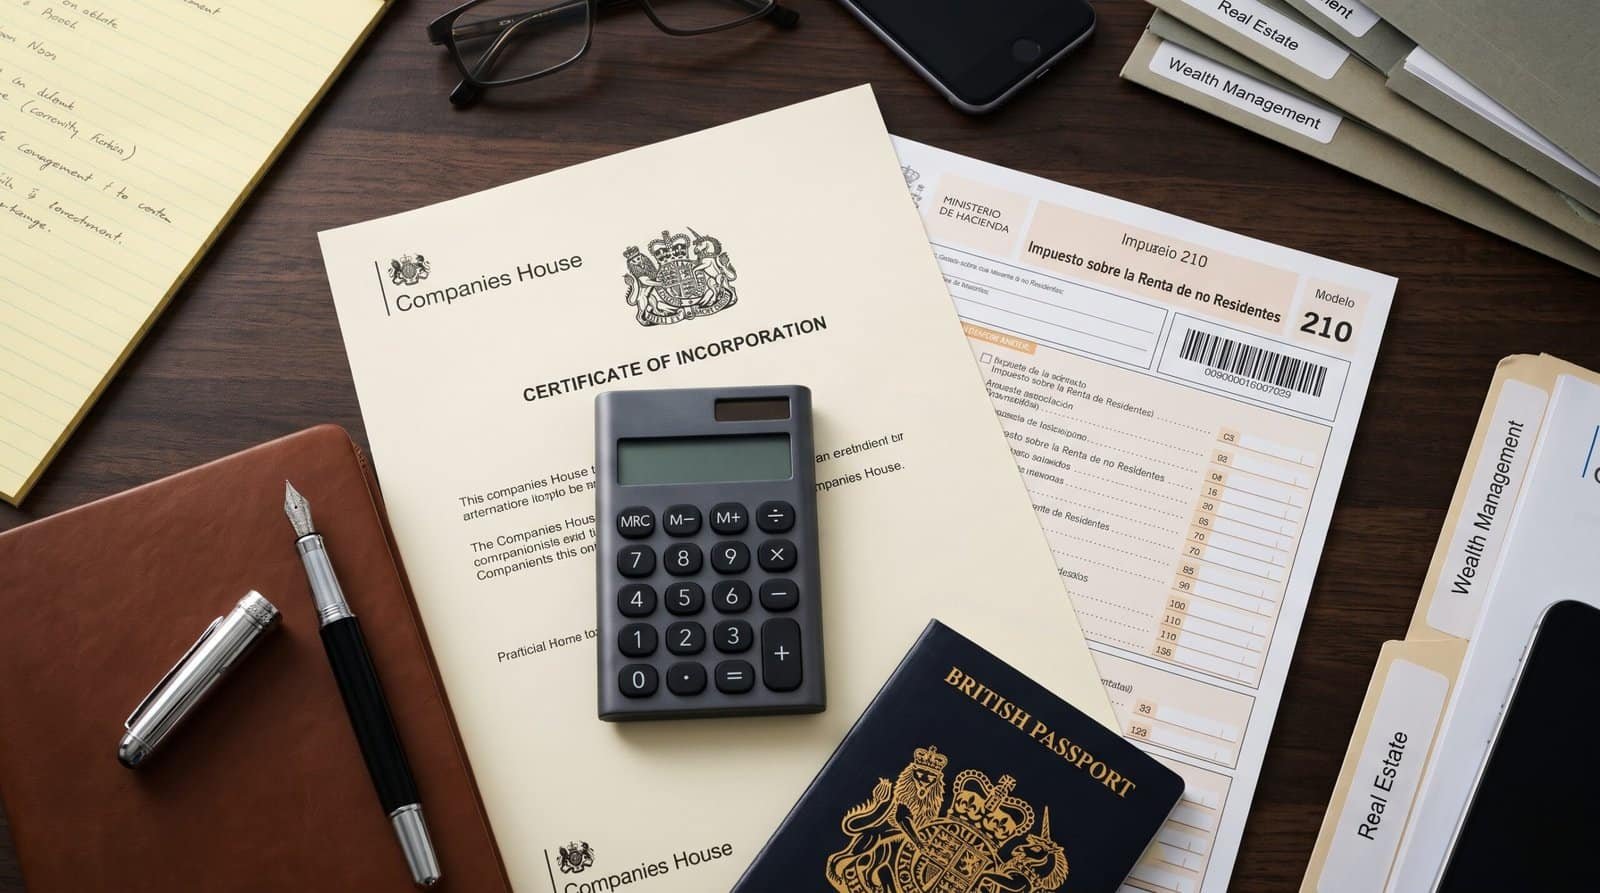
Buying Property in Tenerife via a UK Limited Company: Tax Implications and Feasibility
For British high-net-worth investors, acquiring luxury real estate in Costa Adeje through an existing UK Limited Company was historically a popular strategy for liability protection and inheritance tax planning. However, the fiscal landscape has drastically shifted. Post-Brexit, UK corporate entities are classified as Non-EU residents by the Spanish Tax Agency (AEAT), triggering a cascade of punitive tax rates and aggressive anti-avoidance scrutiny.
While corporate structuring remains highly effective for multi-million-euro commercial portfolios, using a UK Limited Company to acquire a single luxury villa in La Caleta for personal use or seasonal renting is now fraught with fiscal friction.
Here is the analytical breakdown of the tax implications, compliance requirements, and the true feasibility of buying Tenerife real estate through a UK corporate vehicle.
1. The Post-Brexit Reality: The 24% Gross Taxation Trap
The most severe financial drawback of using a UK Limited Company to hold Spanish residential property is the taxation of rental yields.
- The Non-EU Rate: If your UK company rents out the Tenerife villa, the income is subject to the Spanish Non-Resident Income Tax (IRNR). Because the UK is no longer in the EU or EEA, the tax rate is a flat 24%(compared to 19% for EU entities).
- Zero Expense Deductions: This is the critical blow to your ROI. Unlike EU-based companies, a UK Limited Company cannot legally deduct any property-related expenses from its Spanish tax bill. You cannot offset property management fees, community fees (cuotas de la comunidad), IBI (local municipal tax), mortgage interest, or maintenance costs. You pay 24% on every single euro of gross income generated.
2. The Deemed Income Tax (The “Empty Home” Penalty)
Many investors mistakenly assume that if the UK company holds the villa strictly for the directors’ private use and does not rent it out, no Spanish tax is due. This is legally incorrect.
- Imputación de Rentas: Spain applies a “Deemed Income” tax on non-resident property owners (both individuals and corporate entities) who leave their properties vacant or use them solely for personal holidays.
- The Calculation: The Spanish tax office assumes the property generates a theoretical income, usually calculated as 1.1% or 2% of the property’s Cadastral Value (depending on when the value was last revised). Your UK company must file an annual tax return (Modelo 210) and pay the 24% Non-EU tax rate on this theoretical amount. Essentially, it is an annual tax on the privilege of holding an un-rented asset in Spain.
3. Corporate Scrutiny and “Shell Company” Risks
The AEAT has become increasingly aggressive in auditing foreign corporate structures to combat money laundering and tax evasion.
- Piercing the Corporate Veil: If your UK Limited Company has no employees, no other commercial activity,and its sole asset is a luxury villa in Tenerife, the Spanish tax authorities may classify it as a “patrimonial” or shell company.
- The UBO Risk: If the AEAT determines the corporate structure was created solely to obscure the Ultimate Beneficial Owner (UBO) or avoid wealth and inheritance taxes, they possess the legal authority to “look through” the company. They can tax the director or shareholders as private individuals, often applying heavy administrative penalties for tax avoidance.
4. Administrative Friction: NIF, NIE, and KYC
Acquiring the asset requires bridging UK corporate law with Spanish property registries, introducing significant legal and administrative costs before you can even sign a deposit contract.
- Corporate Legalization: The UK company must prove its legal standing. This requires obtaining a Certificate of Good Standing from Companies House, translating all corporate bylaws via an official sworn Spanish translator (traductor jurado), and legalizing them with a Hague Apostille.
- Dual Identification: The UK Limited Company must obtain a Spanish Corporate Tax ID (NIF – Número de Identificación Fiscal). Simultaneously, the company director (or the legal representative signing the deed) must obtain a personal Foreigner Identification Number (NIE).
- Banking KYC (Know Your Customer): Spanish banks enforce extreme compliance checks on non-EU corporate entities opening accounts for property transactions. Proving the exact origin of funds and mapping the corporate ownership tree will delay the capital deployment timeline by several weeks.
5. The Exit Strategy: The 3% Retention Rule
When the UK Limited Company eventually divests from the asset and sells the Tenerife property, the transaction is subject to standard non-resident retention rules.
- The 3% Withholding: At the Notary, the buyer is legally mandated to withhold 3% of the total purchase price and pay it directly to the Spanish Tax Authority. This acts as an advance security payment against the UK company’s final Spanish Capital Gains Tax liability.
- The Reclaim Process: If the final capital gains tax owed is less than the 3% withheld, the UK company must file a complex return to reclaim the difference, a process that can take up to 12 months and requires flawless accounting records of the original purchase costs and structural improvements.
For private investors and families, the extreme administrative burden, the 24% gross taxation on rental income without deductions, and strict banking scrutiny mean that acquiring a Tenerife villa directly in your personal name—or via a newly incorporated Spanish SL (Sociedad Limitada)—is almost always vastly superior to utilizing an existing UK Limited Company.