Non-Resident Mortgages in Tenerife: LTV Limits, Risk Profiles, and Banking Realities (2026)
Securing a mortgage in Spain as an international buyer is a standard procedure, but approaching Spanish retail banks with non-resident income requires a clear understanding of risk assessment metrics. Foreign investors looking to acquire property in Costa Adeje cannot rely on the financing terms typically granted to domestic tax residents.
Spanish financial institutions evaluate foreign capital through conservative risk parameters governed by the Mortgage Credit Law (Ley de Contratos de Crédito Inmobiliario). Understanding how local lenders calculate liquidity, currency risk, and property valuation is essential before committing capital to an earnest money agreement (Contrato de Arras).
1. Loan-to-Value (LTV) Caps for Non-Residents
While Spanish tax residents can frequently obtain up to 80% financing on residential property, foreign non-residents are subject to stricter leverage limits.
- Standard Non-Resident LTV: Spanish banks generally cap mortgage lending for non-resident buyers between 60% and 70% of the property’s valuation.
- The Valuation Metric: The bank calculates the financing percentage on the purchase price or the official independent appraisal value (tasación homologada by entities like Tinsa or Sociedad de Tasación), whichever figure is lower.
- Total Equity Requirement: Because transfer taxes (ITP at 6.5% or IGIC at 7%), notary fees, and registration costs total approximately 10% to 11% in additional closing expenses, a non-resident buyer securing a 70% mortgage must hold a minimum of 40% to 42% in liquid cash to complete the transaction.
2. The Debt-to-Income (DTI) Threshold: 30% to 35%
Spanish underwriting departments assess mortgage viability strictly through your Debt-to-Income ratio (Capacidad de Endeudamiento).
- The Global Calculation: Under local banking standards, all of your existing debt obligations worldwide (mortgages, credit lines, vehicle leases) combined with the projected Spanish mortgage payment cannot exceed 30% to 35% of your verifiable net monthly income.
- Documentation Rigor: Foreign applicants must supply certified documentation covering the previous two tax years, bank statements for the last six months, and official credit reports from their home country (such as Experian in the UK or SCHUFA in Germany).
3. Non-Euro Income and the Article 20 Currency Barrier
If your primary income is denominated in a non-Euro currency (such as British Pounds, US Dollars, or Swiss Francs), securing a Spanish mortgage involves an additional layer of regulatory friction.
- Article 20 Protections: Spanish credit regulations grant non-Euro borrowers the legal right to convert their foreign currency mortgage into their local currency under specific conditions to avoid severe exchange-rate shocks.
- The Banking Reaction: Because this conversion right creates balance sheet risk for Spanish lenders, many domestic institutions refuse to issue mortgages to buyers whose primary income is non-Euro, or they offset the risk by reducing the maximum LTV cap to 50% or 60%. Engaging specialized cross-border mortgage brokers who partner with international desks (such as Sabadell, CaixaBank, or Bankinter) is necessary to navigate this restriction.
4. Mandatory Timeline: The FEIN and the 10-Day Reflection Period
Securing mortgage approval in Spain is legally structured to protect the consumer, but the mandatory cooling-off period requires advance scheduling.
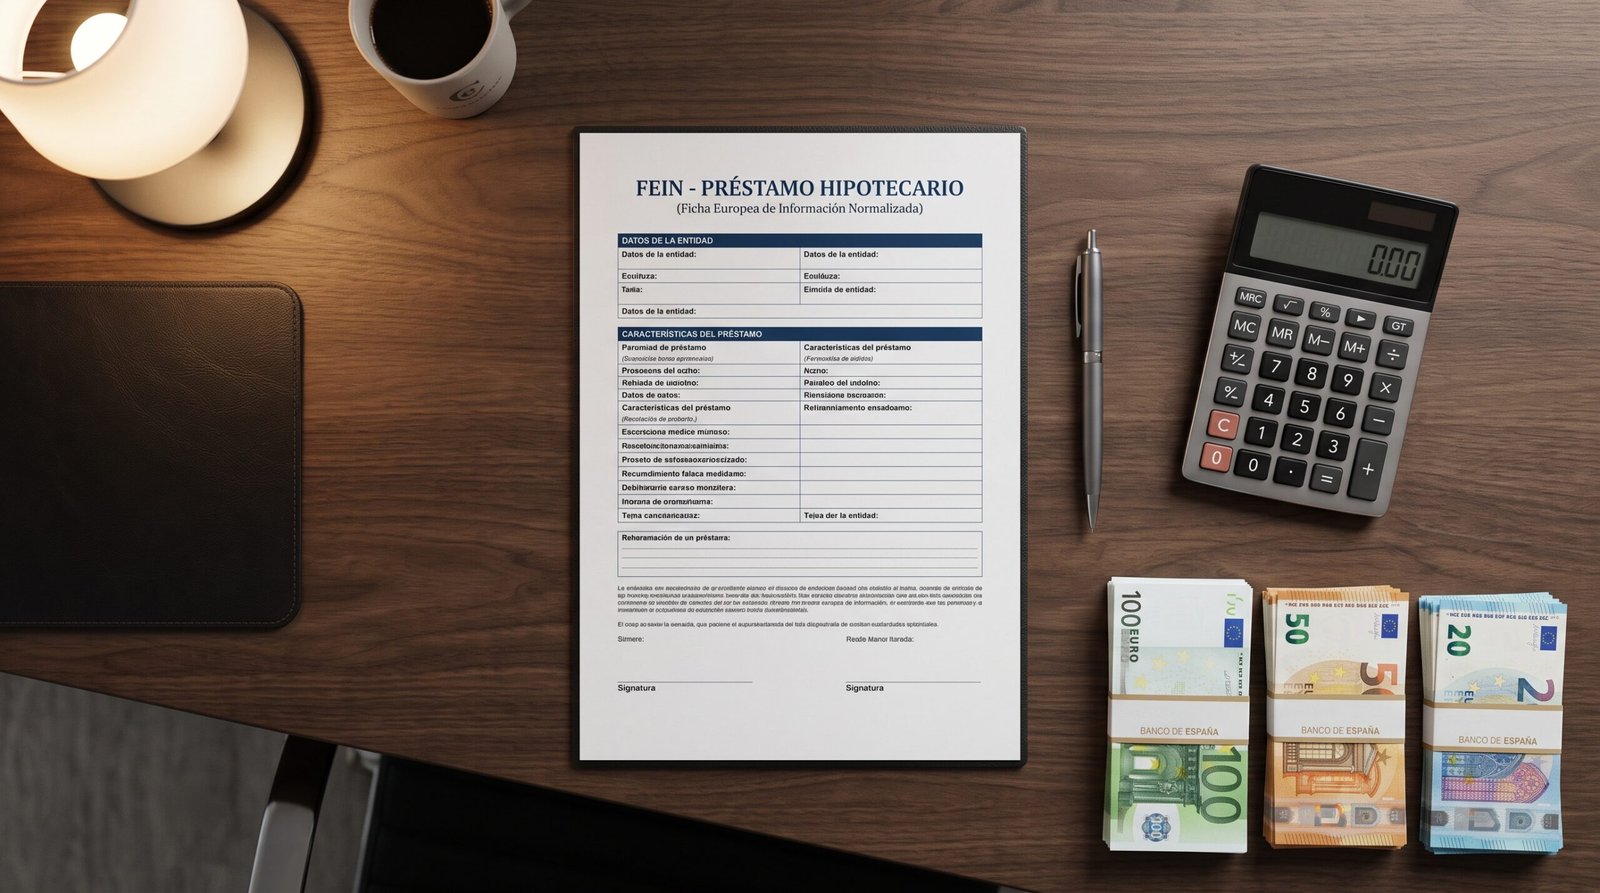
- The Binding Offer (FEIN): Once the bank approves your risk profile, they issue the Ficha Europea de Información Normalizada (FEIN). This document represents a binding offer that locks your interest rates and conditions.
- The 10-Day Cooling-Off Rule: By Spanish law, you cannot sign the mortgage or purchase deed at the Notary Public until at least 10 calendar days have elapsed since the formal receipt of the FEIN.
- The Pre-Act (Acta Previa): During this 10-day period, the buyer (or their legal representative holding a Power of Attorney) must attend the Notary office without the bank present to complete an assessment test, verifying they understand all financial clauses and interest rate terms.
Navigating Spanish lending criteria and securing favorable borrowing terms requires precise financial presentation; coordinating with bilingual mortgage specialists and independent legal counsel well ahead of signing deadlines ensures your acquisition proceeds smoothly without risking your initial deposit.