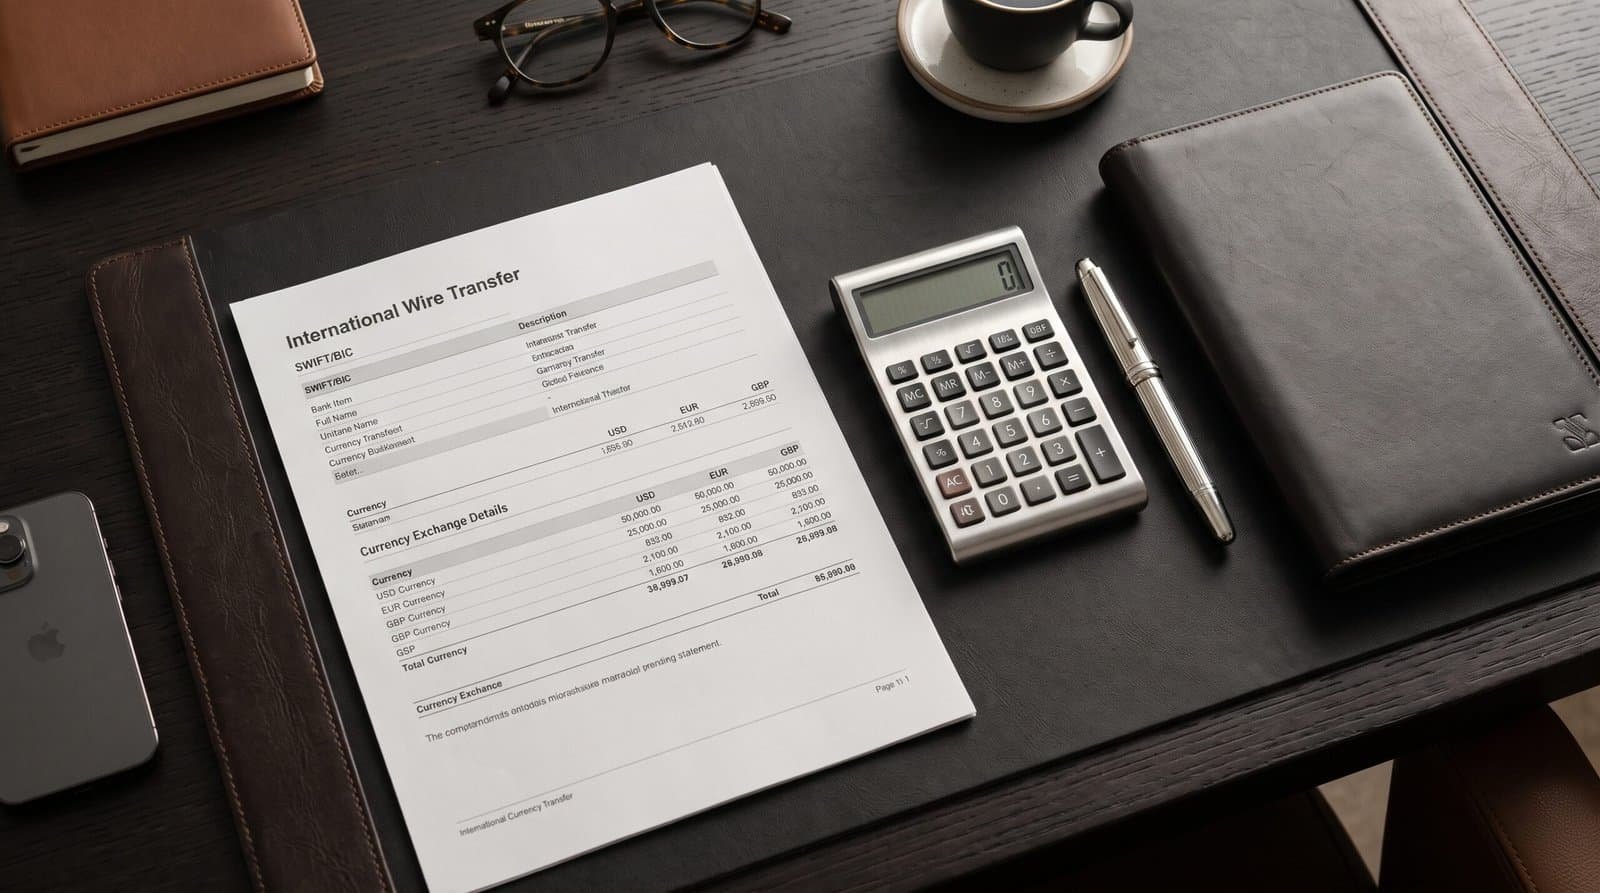
Capital transfers and FX strategies for Spanish property purchases
When international buyers from the United Kingdom, the United States, or Switzerland negotiate a luxury property purchase in Costa Adeje, they typically scrutinise agency commissions, notary fees, and property transfer taxes down to the last percentage point. Yet one of the largest transactional costs in a cross-border acquisition is frequently overlooked: the foreign exchange (FX) spread applied when converting GBP, USD, or CHF into Euros.
On a €1,500,000 villa purchase, a seemingly modest 2.5% to 3.5% exchange rate margin charged by a high-street retail bank translates into €37,500 to €52,500 in avoidable conversion costs. Structuring the currency transfer and payment mechanics early in the buying process is a straightforward way to preserve capital and eliminate exchange rate volatility between signing the deposit contract and completing at the Notary.
High-street banks vs. regulated FX brokers
Traditional retail banks rarely advertise explicit wire fees as their primary profit centre; instead, they build a wide margin into the exchange rate they quote relative to the interbank mid-market rate. For international transfers, retail bank spreads routinely sit between 2% and 4%.
By contrast, specialist FX brokerages regulated by authorities such as the UK Financial Conduct Authority (FCA) or European central banks operate on significantly tighter spreads—typically between 0.3% and 0.8%, depending on the transfer volume. For high-value property transactions, these brokers assign a dedicated dealer who can execute trades directly against live market pricing and issue the formal AML traceability certificates required by Spanish Notaries.
Managing timeline volatility with forward contracts
A standard property acquisition in Tenerife involves a gap of 60 to 90 days between signing the Contrato de Arras(where the buyer commits to a fixed Euro purchase price) and signing the final Escritura at the Notary. If the buyer holds their capital in pounds sterling or US dollars, a 3% adverse currency movement during those two months immediately increases the effective cost of the villa by tens of thousands of pounds or dollars.
To neutralise this exposure, buyers can utilise two primary FX instruments:
- Spot contracts: Buying Euros at the live market rate for immediate delivery (usually within one to two business days). This is standard for the initial 10% deposit.
- Forward contracts: Locking in today’s exchange rate for a future settlement date (up to 12 months ahead). The buyer typically deposits 5% to 10% of the contract value upfront as margin with the FX provider, and settles the remaining balance in their home currency just before completion. This fixes the exact cost of the villa in the buyer’s domestic currency from day one, removing market speculation from the purchase.
The Spanish bank cheque (Cheque Bancario) and incoming wire fees
In Spain, the final balance of a property purchase is traditionally handed over at the Notary in the form of a certified Spanish bank cheque (cheque bancario nominativo) issued in the seller’s name, or via a Bank of Spain instant transfer (transferencia OMF).
This introduces a local banking friction point. If a foreign buyer wires €1,350,000 from an overseas FX broker into their newly opened Spanish non-resident bank account, many traditional Spanish retail banks charge a substantial issuance fee to print the cheque bancario—sometimes 0.3% to 0.5% of the cheque’s face value—unless the fee is waived in advance. On a €1.35 million balance, an unnegotiated 0.4% cheque fee adds €5,400 in unnecessary bank charges.
Before opening a Spanish account or wiring completion funds, buyers—or their lawyers acting under a Power of Attorney—should negotiate written confirmation of zero incoming transfer fees and a capped or waived fee for issuing the cheque bancario. Alternatively, some regulated FX providers and Spanish law firms can arrange direct completion via an OMF transfer from a lawyer’s client escrow account, bypassing retail bank cheque fees entirely.
AML traceability for the Notary
Under Spanish Anti-Money Laundering legislation (Law 10/2010), the Notary must record the exact bank account of origin, the IBAN, and the payment method for every euro used in the purchase.
When using an FX broker, the buyer must ensure the broker provides a formal origin of funds certificate linking the domestic bank account (where the GBP or USD originated) to the Euro funds arriving in Spain. Failing to supply this clear chain of custody at least one week before the Notary appointment can result in the Spanish bank freezing the incoming Euros for compliance review, delaying completion.
Establishing a regulated FX account and negotiating Spanish bank cheque fees before signing the Contrato de Arrasensures predictable acquisition costs and smooth capital clearance at completion. Buyers should coordinate their currency strategy directly with their Spanish conveyance lawyer to satisfy all Notary traceability requirements.